What is a CBDC? Central bank digital currency explained
What is a CBDC? How central bank digital currencies work, retail vs wholesale CBDCs, how they differ from stablecoins and bitcoin, and where the digital euro stands.
CryptoGroup Newsroom · · 6 min read
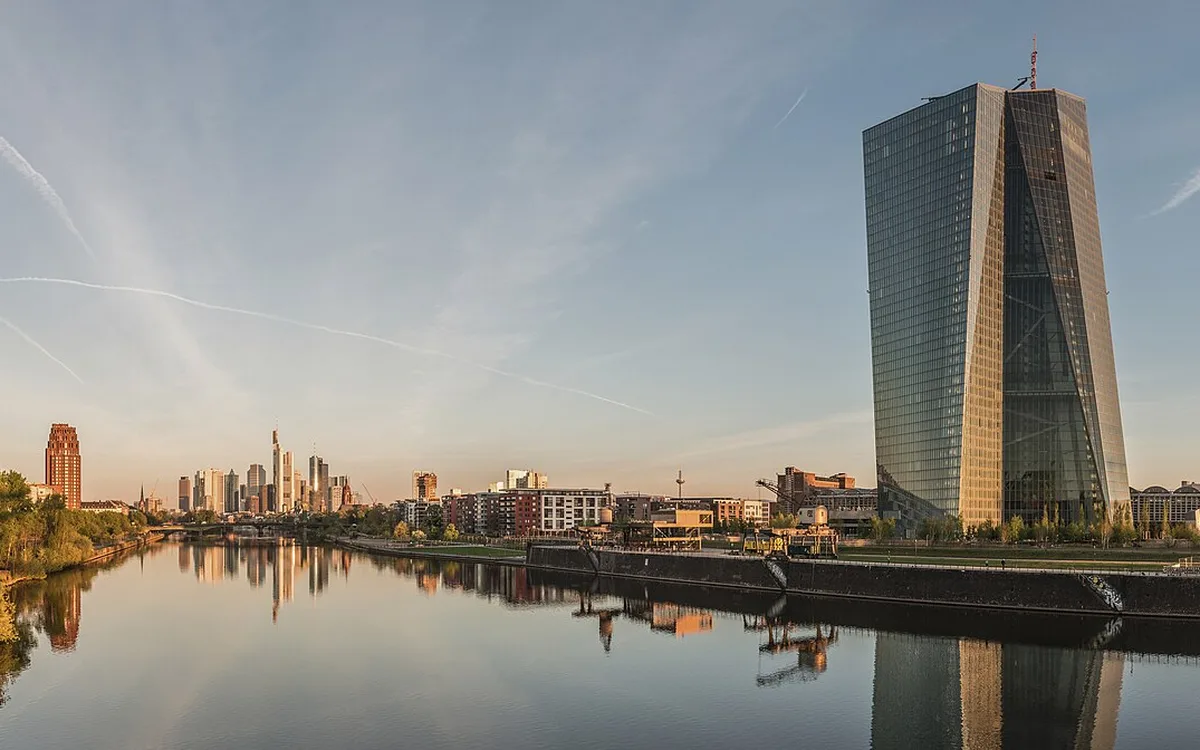
A central bank digital currency (CBDC) is a digital form of a country's money that is issued directly by its central bank. One digital euro would be worth exactly one euro in cash, and it would be a claim on the European Central Bank itself, just like a banknote. That last point is what makes a CBDC different from the money most people already use online.
How a CBDC differs from the money in your bank app
Most "digital money" today is commercial bank money: the balance in your account is a debt your bank owes you. If the bank fails, deposit insurance covers you up to a limit. Cash is different, because it is issued by the central bank and carries no bank risk.
A CBDC is meant to be the digital version of cash. It is a direct liability of the central bank, so the holder does not depend on the health of any private bank. In most designs, commercial banks and payment firms would still run the wallets and apps, while the central bank issues the money and keeps the core ledger.
Retail vs wholesale CBDCs
- Retail CBDC: for the public, to pay in shops, online and between people. The digital euro and Sweden's proposed e-krona are retail projects.
- Wholesale CBDC: only for banks and financial institutions, to settle large transfers and trades in tokenised assets. The Eurosystem's Pontes link for settling tokenised trades in central bank money, which went live in September 2026, and Singapore's earlier Project Orchid research belong in this category.
Wholesale projects get less attention but are moving faster, because they change little for ordinary users and fit into existing bank plumbing.
CBDC vs stablecoin vs bitcoin
People often lump these together. They are very different things:
| CBDC | Stablecoin | Bitcoin | |
|---|---|---|---|
| Issued by | Central bank | Private company | No issuer; mined by the network |
| Value | Always 1:1 with the national currency | Pegged, backed by reserves the issuer holds | Floats freely on the market |
| Who you rely on | The central bank | The issuer and its reserves | The network's rules and your own key security |
| Privacy | Set by law and the central bank's design | Issuer can freeze addresses | Public ledger, pseudonymous |
| Examples | Sand Dollar, eNaira, e-CNY (pilot) | USDT, USDC, HSBC RedCoin | BTC |
A stablecoin tries to give private-sector tokens the stability of a national currency, and is now regulated under laws such as the EU's MiCA and the US GENIUS Act. Bitcoin has no issuer at all. A CBDC is the state's own answer to both.
Why central banks want one
- Keeping public money relevant. As cash use falls, people could lose access to central bank money altogether. In Sweden, just 5% of people surveyed paid with cash for their last purchase, according to Riksbank data cited by CoinDesk.
- Monetary sovereignty. Central banks worry that foreign-currency stablecoins or another region's CBDC could replace the local currency in everyday payments. Sweden's Riksbank has cited both the digital euro and foreign stablecoins as reasons to prepare a law for a digital krona.
- Resilience. A CBDC can be designed to work offline, as a backup if card networks, power or telecom links go down.
- Cheaper, faster payments, including across borders, which is also the goal of regional projects built on stablecoins and tokenised deposits.
The worries
- Privacy. A central bank ledger could, in theory, let the state see every payment. Most proposals promise strong privacy rules, and the digital euro is designed so the ECB would not see who pays whom, but critics say laws can change.
- Bank runs. If people could move savings instantly from banks into a risk-free CBDC, banks could lose deposits in a crisis. That is why the digital euro would pay no interest and come with holding limits.
- Control. Programmable money could be restricted in how it is spent. Central banks in Europe say they will not do this, but the concern drives much of the political opposition.
Where CBDCs stand in 2026
More than 130 countries and currency unions have explored a CBDC, according to the Atlantic Council's CBDC tracker, but full launches are rare.
Key moments
Oct 2020
Sand Dollar
The Bahamas launches the first nationwide retail CBDC.
2020 onward
e-CNY pilots
China runs the largest CBDC trials in a growing list of cities.
Oct 2021
eNaira
Nigeria becomes the first large economy to launch a retail CBDC.
Jan 2025
US executive order
President Trump bars federal agencies from creating or promoting a US CBDC.
Sep 2026
Digital ruble
Russia's largest banks are required to start offering the digital ruble to clients.
H2 2027
Digital euro pilot
The ECB plans a 12-month pilot, with a possible first issuance in 2029 if EU law is adopted.
The digital euro is the project most likely to affect crypto users in Europe. ECB President Christine Lagarde has tied its 2027 pilot to EU lawmakers adopting the regulation. The United States has gone the other way, backing regulated dollar stablecoins instead of a CBDC.
What a CBDC means for crypto holders
A CBDC would not replace bitcoin or other cryptocurrencies, and it would not be traded on crypto exchanges in the way a stablecoin is. It competes most directly with stablecoins and bank payment apps. For crypto users the practical questions are whether exchanges will be allowed to accept CBDC deposits, and how holding limits and privacy rules will work once one launches. Until then, nothing changes for the coins you already hold.
Frequently asked questions
Is a CBDC a cryptocurrency?
No. A CBDC is issued and controlled by a central bank and is always worth exactly one unit of the national currency. It may or may not use blockchain technology, but it is not decentralised and its supply is not fixed by code.
Will a CBDC replace cash?
Central banks planning one, including the ECB and the Riksbank, say a CBDC would sit alongside cash rather than replace it.
Which countries have a CBDC?
The Bahamas, Jamaica and Nigeria have launched retail CBDCs, and the Eastern Caribbean ran one as a pilot. China runs a very large e-CNY pilot, and Russia has started rolling out the digital ruble through its largest banks.
Does the United States have a CBDC?
No. A January 2025 executive order bars federal agencies from creating or promoting one, and US policy now favours regulated private stablecoins.
What is the difference between a CBDC and a stablecoin?
A CBDC is a direct claim on the central bank. A stablecoin is issued by a private company that promises to redeem it at face value and holds reserves to back that promise.
This article is for information only and is not financial advice. Crypto assets are volatile; do your own research. Read our disclaimer
More from Regulation
View all →Read next
Bitcoin ETFs lose $635M in a day, October flows turn negative
US spot bitcoin ETFs saw $635M of net outflows on Thursday, the most since June, wiping out October's gains. Ether ETFs lost $111M; XRP funds took in cash.
HSBC launches RedCoin, its HKD stablecoin, for 3.3M PayMe users
HSBC RedCoin (RCHKD), the bank's first stablecoin, goes live on PayMe in Hong Kong for transfers and payments at 100,000+ merchants. Five things to know.
Bitcoin Core drops embargoes for bugs AI can find in one prompt
Bitcoin Core will patch 'easily discoverable' vulnerabilities right away in every maintained version, saying AI makes such flaws too easy to rediscover to keep secret.