BIS paper: higher bank deposit rates slow stablecoin growth
A BIS working paper finds stablecoins grow more slowly when US banks pay savers more, with a stronger effect for USDC than USDT. What it does and doesn't show.
CryptoGroup Newsroom · · 2 min read
On this page
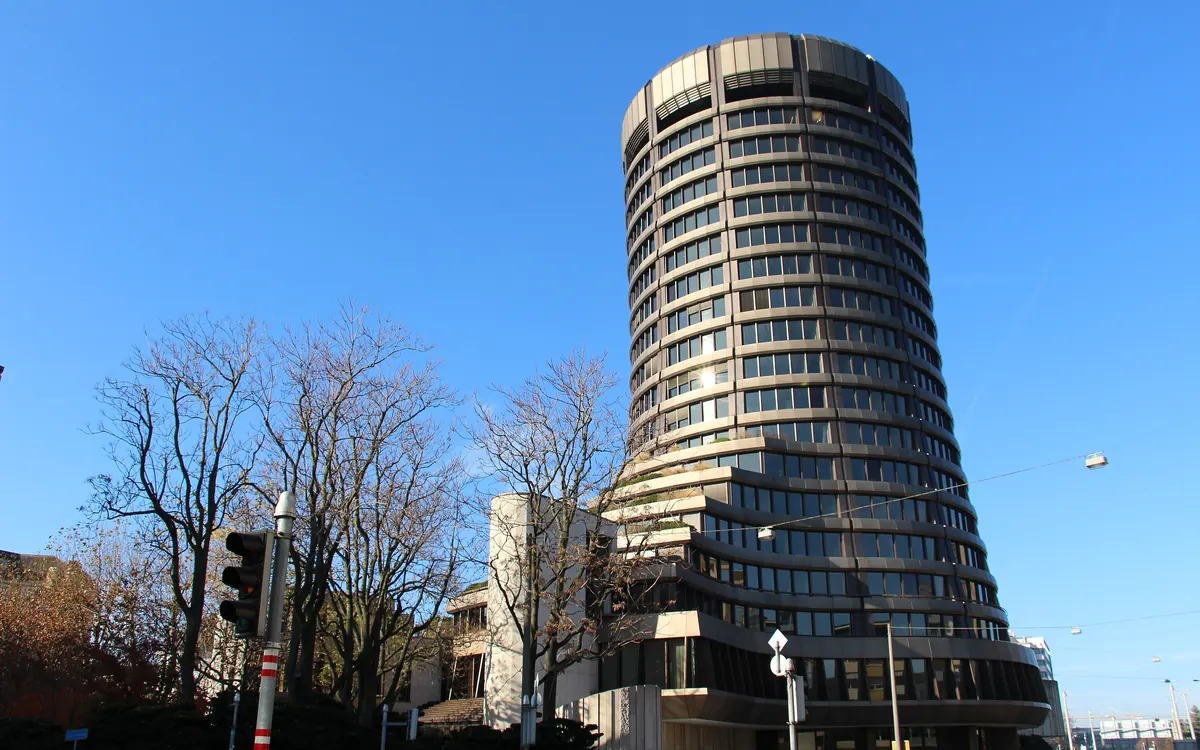
Banks may be able to slow the rise of stablecoins simply by paying savers more, according to a working paper from the Bank for International Settlements (BIS). The study, Are stablecoins and bank deposits substitutes? by Rashad Ahmed and Iñaki Aldasoro (BIS Working Paper No. 1382), concludes that the two are partial substitutes: higher deposit rates are followed by slower stablecoin growth. CoinDesk reported the findings on Saturday.
What the researchers measured
The authors used weekly US data from January 2019 to June 2025, controlling for factors such as bitcoin prices, Treasury yields and financial conditions. The headline results:
| Scenario | Average 10-week stablecoin market-cap growth |
|---|---|
| Baseline (sample average) | ~15% |
| After a 1 bp deposit-rate rise, simple (OLS) estimate | ~12% |
| After a 1 bp rise, instrumental-variable estimate (~3x larger effect) | ~6% |
To separate cause from coincidence, the authors relied on a quirk in how banks set rates: they pass on Federal Reserve moves to depositors much more aggressively once the fed funds rate is above roughly 3%. They flagged some weakness in that method, while noting it passed a placebo test using non-stablecoin crypto assets.
USDC more sensitive than USDT
The effect was stronger for Circle's USDC than for Tether's USDT, which the authors link to USDC's closer ties to US depositors. Bitcoin showed no comparable response — a sign the pattern is about where people park dollars, not general crypto appetite.
What it does not show
The paper analyses how money is split between assets. It does not establish that stablecoin growth reduces overall bank deposits or lending, and the sample covers a single high-rate period. Results could change as yield-bearing stablecoins and tokenised money-market funds spread.
Why it matters
The question sits at the heart of the US stablecoin debate. Bank of America CEO Brian Moynihan warned in January that up to $6 trillion in deposits could move into stablecoins and similar products, CoinDesk noted. The BIS authors say banks "retain some influence over the pace of that adoption through deposit pricing." For a primer on how these tokens work, see what is a stablecoin; for the issuer side, read our report on how Circle splits USDC revenue with partners.
This article is for information only and is not financial advice. Crypto assets are volatile; do your own research. Read our disclaimer
More from Regulation
View all →Read next
Goldman, Wells Fargo, Morgan Stanley bet on tokenization
Q3 earnings calls showed how Goldman Sachs, Wells Fargo and Morgan Stanley each expect to profit from tokenization: more trading, faster payments, more advice.
Ether margin longs on Bitfinex climb as prices stall
Bitfinex traders hold about 367,500 ETH in margin longs against under 9,000 ETH in shorts, while bitcoin and ether trade flat into a quiet Saturday evening.
Fidelity's Solana health check: reliable, but too concentrated
Fidelity's FCAT says Solana has gone two years without a major outage, yet 18 validators, one host and two EU cities hold an outsized share of its stake.