USDT vs USDC: which stablecoin should you use?
USDT vs USDC compared: issuers, reserves, audits, regulation in the EU and US, networks, fees and depeg history, plus which dollar stablecoin fits which use.
CryptoGroup Newsroom · · 7 min read
Quick verdictUSDT wins on reach and liquidity, especially on Tron and with P2P traders; USDC wins on transparency and regulatory status in the EU and US. Many people sensibly hold both.
Jump to the verdict ↓On this page
USDT (Tether) and USDC (USD Coin) are the two biggest dollar stablecoins, and for most everyday purposes one is worth about the same as the other: $1. The differences are in who stands behind them, how they report their reserves, where they are legal to offer and which blockchains they run on. Those details decide which one is better for you. If stablecoins are new to you, start with what a stablecoin is.
The short version
| USDT (Tether) | USDC (Circle) | |
|---|---|---|
| Issuer | Tether, headquartered in El Salvador | Circle, a U.S. company listed on the NYSE |
| Launched | 2014 | 2018 |
| Market cap (CoinGecko, 24 Oct 2026) | about $182.5 billion | about $71.6 billion |
| Reserve reports | Quarterly attestations (BDO) | Monthly attestations (Deloitte) |
| EU (MiCA) status | Not authorised; restricted for EEA users on major exchanges | Authorised e-money token |
Who issues them
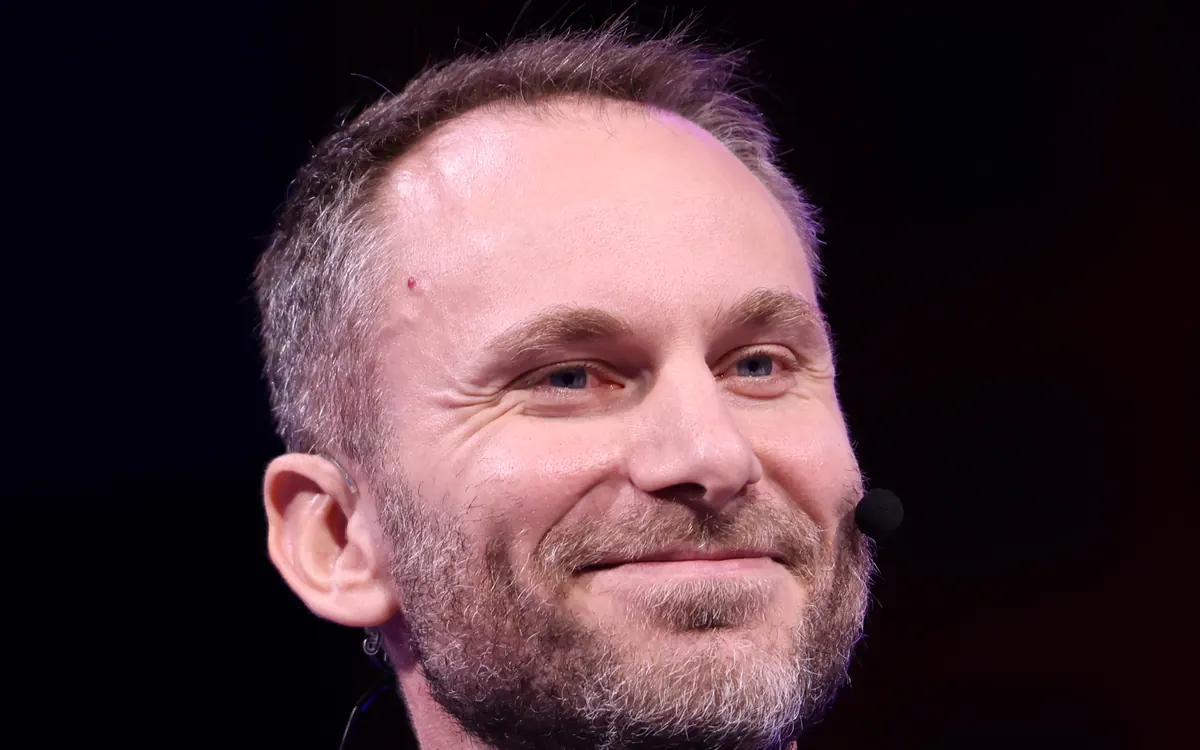
Tether launched USDT in 2014 and moved its headquarters to El Salvador in 2025. It is privately owned and, beyond stablecoins, has become a large investor in bitcoin mining, AI and other ventures. CEO Paolo Ardoino (pictured) is its public face.
Circle launched USDC in 2018, originally with Coinbase. It listed its shares on the New York Stock Exchange in June 2025, which means audited financial statements and public quarterly results. Its revenue comes from interest on reserves, much of which it shares with partners such as Coinbase; we covered how $819 million of first-half USDC revenue went to partners and costs.
Reserves and transparency
Both issuers say every token is backed by at least a dollar of assets, and both let verified institutions redeem tokens for dollars directly. Ordinary users usually go through an exchange instead.
- USDT: reserves are mostly U.S. Treasury bills, repo and cash, but Tether also holds gold, bitcoin and secured loans. An accounting firm, BDO, publishes quarterly attestations of the reserves at a single date; this is less than a full audit.
- USDC: reserves are held as cash at banks and in the Circle Reserve Fund, an SEC-registered money-market fund managed by BlackRock. Deloitte issues monthly attestations, and Circle publishes weekly reserve breakdowns.
In practice, USDC's reserves are simpler and reported more often, while USDT carries extra assets that can earn more but also fluctuate.
Regulation in the EU and the US
- European Union: under MiCA, only authorised issuers can offer stablecoins to the public. USDC is authorised as an e-money token through Circle's French entity, and the EBA has named it the EU's first significant e-money token, with joint supervision starting 12 November 2026. USDT is not authorised, so major exchanges have restricted it for EEA users.
- United States: the GENIUS Act sets federal rules for payment stablecoins and takes effect on 18 January 2027. Circle is building toward that regime. Tether launched a separate U.S. token, USA₮ (USAT), in January 2026, issued by Anchorage Digital Bank; it is far smaller than USDT, at about $183 million in late October, and says USDT itself is progressing toward GENIUS Act compliance.
Networks and fees
USDT and USDC exist on many blockchains, and the network must match on both ends of a transfer.
- USDT is used most on Tron and Ethereum, plus Solana, TON and others. Tron's low fees make USDT the default for P2P trading and remittances in many countries.
- USDC is strongest on Ethereum, Solana, Base and Arbitrum. Circle's Cross-Chain Transfer Protocol (CCTP) moves USDC between chains by burning on one and minting on another, which avoids the extra risk of wrapped tokens on a bridge.
Our guide to storing USDT walks through networks and wallets step by step; the same rules apply to USDC.
Track record under stress
Neither coin has a perfect history. USDT dipped to roughly $0.95 in May 2022 during the Terra collapse and recovered within days as Tether processed billions in redemptions. USDC fell to about $0.87 in March 2023 after Circle disclosed $3.3 billion of reserves held at the failed Silicon Valley Bank; it regained its peg once U.S. authorities guaranteed the bank's deposits.
Both issuers can freeze addresses and regularly do so at the request of law enforcement, which also means a mistaken or contested freeze is possible.
Pros and cons
USDT
+ Pros
- Largest stablecoin with the deepest trading liquidity
- Cheap transfers on Tron; widely accepted in P2P markets
- Supported by almost every exchange outside the EU
− Cons
- Not authorised under MiCA in the EU
- Quarterly attestations only; reserves include gold, bitcoin and loans
- Much of its retail use runs on Tron, a more centralised network
USDC
+ Pros
- Monthly attestations and a simple cash-and-Treasuries reserve
- Authorised under MiCA and issued by a listed U.S. company
- Native on many chains with burn-and-mint transfers via CCTP
− Cons
- Smaller liquidity on many exchange pairs and P2P markets
- Depegged in March 2023 when a reserve bank failed
- Concentrated exposure to the U.S. banking system
Which one fits your use
- Trading on a global exchange or P2P: USDT usually has more pairs and tighter spreads.
- Living in the EU: USDC (or a euro stablecoin) is the practical choice, since USDT is restricted.
- DeFi on Ethereum, Base or Solana: USDC is often the default collateral and lending asset.
- Sending money cheaply: pick whichever both sides support on the same low-fee network.
- Holding larger sums for a while: spreading between two issuers reduces single-issuer risk; keep savings in a wallet you control.
Neither coin pays interest by itself; any yield comes from a platform lending your coins, with its own risk.
Our verdict
USDT for reach, USDC for transparency
USDT is the more liquid, more widely accepted dollar token, and the natural choice for trading and P2P outside Europe. USDC reports its reserves more often, is legal to offer in the EU and is built for the U.S. rules arriving in 2027. Neither is risk-free: they are claims on private companies, not insured deposits. Choose by where you live and which network you use, and do not keep more in either than you can afford to have frozen or delayed.
Frequently asked questions
Is USDC safer than USDT?
USDC is more transparent, with monthly attestations and a simpler reserve, and it is authorised in the EU. USDT has a longer track record and more liquidity. Both carry issuer risk, and both have briefly lost their peg.
Can I swap USDT for USDC at 1:1?
Usually close to 1:1 on exchanges and DEXs, minus a small fee or spread. Rates can move away from parity during market stress.
Why can't I buy USDT on my European exchange?
USDT is not authorised under the EU's MiCA rules, so exchanges serving EEA customers have restricted it. USDC and euro stablecoins remain available.
Do USDT or USDC pay interest?
No, the tokens do not pay holders interest. Any yield comes from exchanges or DeFi protocols lending them out, which adds platform risk.
This article is for information only and is not financial advice. Crypto assets are volatile; do your own research. Read our disclaimer
More from DeFi
View all →Read next
Broadridge's blockchain repo platform handles $359B a day
Broadridge's DLR platform processed an average $359B a day in repo in September. How tokenized repo works, where banks save money and what it cannot fix.
Apex CEO: Clarity Act failure hands Asia and Gulf a crypto edge
Apex Group's Peter Hughes says the stalled US Clarity Act will push digital-asset business to Asia, the Middle East and Bermuda, and calls EU MiCA restrictive.
UAE-led sting flags $39B in scam-linked funds and crypto
Operation Confrontation Ghost, led by the UAE with 30 countries, Interpol and Crypto.com, brought 960+ arrests and flagged $39B+ in fraud-linked funds and crypto.